Storm damage & insurance
Roof insurance
claims,made clear.
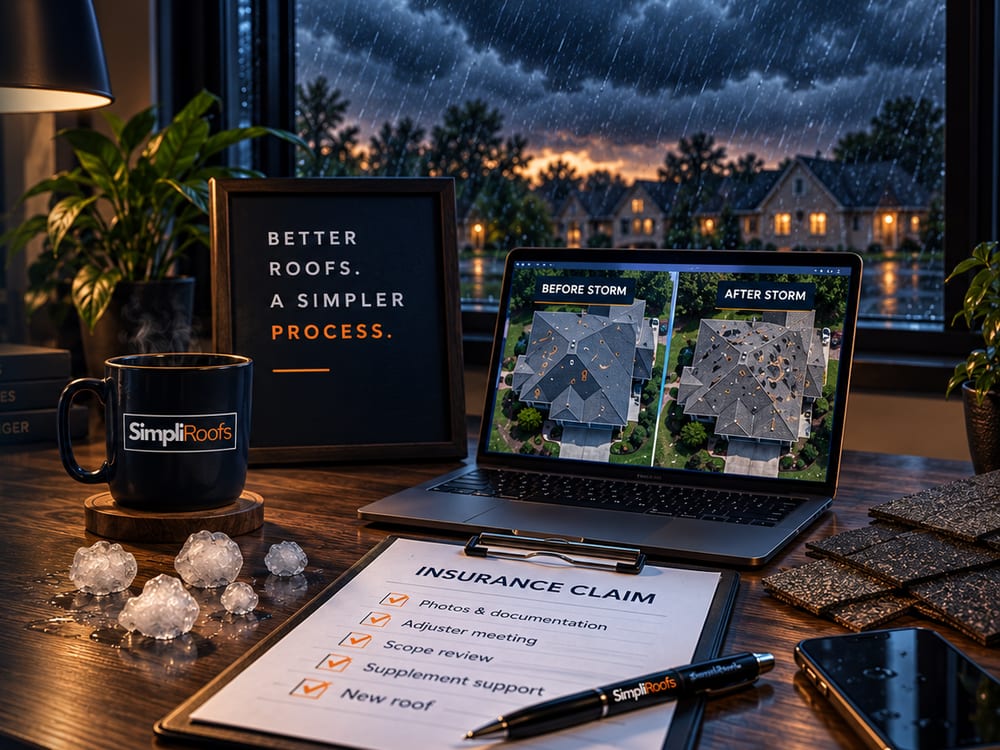
The single most important thing to know: get your roof inspected, documented and quoted before you file. Here is the whole process in three steps, and then in full.
- Trusted
local experts - Quality
craftsmanship - A smoother
experience
- 01Start here
Get inspected and quoted first
Before you file, we inspect and photograph the damage and give you a free, detailed quote documenting the real cost of the work.
- 02
File your claim with our quote in hand
Submit it to your carrier at the time of filing, along with photos of the damage, so they see the actual repair cost from the start.
- 03
Your insurer reviews and settles with you
We meet the adjuster on site. Having the real numbers up front can speed the whole process along. Then we get your roof done.
Why it works
Your quote speaks the adjuster's language.
Insurance adjusters often price claims using Xactimate or QuickMeasure-style methodology, the same approach SimpliRoofs uses. Because the numbers reconcile cleanly, filing with our detailed quote in hand means your carrier sees the actual cost of the work from the start, with less back-and-forth.
What we provide
- A free, detailed quote documenting the real cost of the work.
- Pricing built from actual material and labor cost, itemized line by line.
- A clear document you bring to your insurer yourself.
We work with all major insurance carriers

+ every other carrier.
If you have a policy, we work with it.
- Local expertise
- Honest guidance
- On your side
The basics
Does homeowners insurance cover roof replacement?
Often, yes. But it depends entirely on what caused the damage and the terms of your policy. Here is the general rule of thumb most carriers follow. Your policy is the final word, so always confirm with your insurer.
Typically covered
- Hail damage: bruising, granule loss, and impact cracks from a hailstorm.
- Wind damage: shingles lifted, torn, or blown off in a windstorm.
- Fallen trees or limbs: sudden impact damage from a storm.
- Other sudden, accidental events: the key word insurers look for is "sudden."
Typically not covered
- Age and normal wear: a roof simply reaching the end of its lifespan.
- Lack of maintenance: damage that built up from deferred upkeep.
- Pre-existing damage: problems that existed before the policy or the event.
- Cosmetic-only issues: some policies exclude purely cosmetic damage.
This is general educational information, not a coverage determination. Whether your roof is covered, and how much your insurer pays, is decided solely by your insurance carrier under the terms of your policy.
Know the terms
ACV, RCV, depreciation and your deductible, explained simply.
These four terms decide what your claim actually pays. Understanding them before you file means no surprises later.
- Actual Cash Value
The depreciated value of your roof: replacement cost minus depreciation for age and wear. An older roof has a lower ACV.
Many policies pay the ACV amount first, up front.
- Replacement Cost Value
The full cost to replace your roof with similar materials, with no depreciation deducted.
An RCV policy is designed to cover the complete cost of putting your roof back to new (minus your deductible).
- The held-back portion
The difference between ACV and RCV. On an RCV policy, insurers often pay the depreciated (ACV) amount first and hold back the rest.
That held-back "recoverable depreciation" is typically released after the work is completed and documented, so completing the job is what unlocks it.
- What you pay
The amount you pay out of pocket before insurance contributes. You are always responsible for your deductible. It can't be waived or covered by a contractor.
Example$14,000 approved claim minus a $2,000 deductible: the insurer pays $12,000, you pay $2,000.
Honest information. No surprises.
The full walkthrough
How to file a roof insurance claim, in full detail.
The three-step path above is the short version. Here is everything that happens, from the storm to your finished roof.
- 01
Document the damage
After a storm, safely photograph the damage from the ground: missing or lifted shingles, dents, debris, interior leaks or water stains. Note the date of the storm. The more documentation you have, the smoother your claim.
- 02
Get a SimpliRoofs inspection and quote first
Enter your address for a free, detailed quote in about a minute, or have a specialist walk the roof and photograph what they find. Either way you get the real, transparent cost of the work: the number you bring to your carrier.
- 03
File your claim with the quote in hand
Contact your insurance company to file, and submit your SimpliRoofs quote at the time of filing, along with your damage photos. Because adjusters use the same Xactimate and QuickMeasure-style pricing we do, the numbers reconcile cleanly, so your carrier sees the actual cost from the start.
- 04
The adjuster inspects and your insurer decides
Your carrier may send an adjuster to inspect. We meet the adjuster on site so nothing gets missed, and our photos and documentation support an accurate review. They determine coverage and the settlement amount under your policy. SimpliRoofs isn't a public adjuster.
- 05
We replace your roof, you pay your deductible
Once your claim settles, SimpliRoofs completes the work to our standards: our certified crews, photo documented, backed by our 25-year workmanship warranty. You're responsible for your deductible; your insurer settles the rest directly with you.
Don't climb onto a storm-damaged roof yourself. It's unsafe. Photos from the ground are enough to start, and our inspection is free.
Clear expectations
What SimpliRoofs does and doesn't do.
We keep our role simple and transparent. Here is exactly where SimpliRoofs fits in the insurance process, and where your carrier takes over.
What SimpliRoofs does
- Does insurance and storm-damage roof work across Dayton, Cincinnati and the Miami Valley.
- Inspects and documents the damage and gives you a free, detailed quote your carrier can work from.
- Meets the adjuster on site and explains the paperwork in plain English: scope, depreciation, supplements.
- Replaces your roof to SimpliRoofs' standards once your claim is settled.
What SimpliRoofs doesn't do
- We don't adjust, negotiate, or settle your claim. SimpliRoofs isn't a public adjuster, and you file with your own carrier.
- We don't determine coverage or guarantee that a claim will be approved. Your carrier decides that under your policy.
- We can't waive or discount your deductible. That isn't legal, and your deductible is always yours to pay.
- We don't give insurance or legal advice. For coverage questions, talk to your carrier or a licensed professional.
Same communities. A higher standard.

Insurance FAQ
Your questions, answered.
The questions homeowners ask most about roof insurance claims. If yours is not here, text us and a real person will answer it.
Text us (937) 966-2141- Real people
real answers - Honest
information - Local experts
you can trust
It depends on the cause of the damage and your policy. Insurers generally cover roof damage from sudden, accidental events like hail, windstorms, and fallen trees. Damage from age, normal wear, or lack of maintenance is typically not covered. Whether your specific roof is covered, and how much your insurer pays, is determined solely by your carrier under your policy. Always confirm with your insurer.
ACV (Actual Cash Value) is the depreciated value of your roof: replacement cost minus depreciation for age and wear. RCV (Replacement Cost Value) is the full cost to replace it with similar materials. Many policies pay the ACV first, then release the remaining recoverable depreciation after the work is completed and documented. Your policy type determines which applies, so confirm with your carrier.
Your deductible is the amount you pay out of pocket before your insurance contributes. If your approved claim is $14,000 and your deductible is $2,000, your insurer pays $12,000 and you pay $2,000. You are responsible for paying your deductible. It can't legally be waived or covered by a contractor, and a homeowner cannot profit from an insurance claim.
We recommend getting a SimpliRoofs inspection and quote first, then filing your claim with that quote in hand. Submitting a transparent, detailed quote to your carrier at the time of filing means they see the actual cost of the work from the start, which can help speed up the process.
It can, depending on your insurer, your claims history, and whether the damage came from a widespread weather event. Many carriers treat weather-related claims differently from other types. Because this varies, ask your insurance company directly how a claim might affect your premium before you file.
If your claim is denied, your insurer must provide a reason. You can request a re-inspection, provide additional documentation (photos, a detailed contractor estimate), or use your carrier's appeals process. SimpliRoofs isn't a public adjuster, but our transparent detailed quote can serve as clear documentation of the actual repair cost. For disputes, you may also consult a licensed public adjuster.
Most policies have a filing deadline after the date of loss, often several months to a year, but it varies by carrier and state. File as soon as you reasonably can after discovering damage; delays can complicate a claim. Check your specific policy or ask your carrier for the exact deadline.
Yes. SimpliRoofs does insurance and storm-damage roof work across Dayton, Cincinnati and the Miami Valley. If hail or a windstorm damaged your roof, we guide you through the roofing side of the claim: we inspect and document the damage, give you a free, detailed quote in the same Xactimate/QuickMeasure-style format your carrier uses, meet the adjuster on site, explain the paperwork in plain English, and replace your roof to our standards once your claim is settled. You file with your own carrier and they decide what's covered. SimpliRoofs isn't a public adjuster, so we don't adjust, negotiate, or settle your claim for you, and your deductible is always yours.
Insurance adjusters often use Xactimate or QuickMeasure-style pricing, the same methodology SimpliRoofs uses. Because the pricing reconciles cleanly, filing your claim with a SimpliRoofs quote in hand means your carrier sees the actual cost from the start, which can reduce back-and-forth and help speed up the process.
No. In most cases you have the right to choose your own roofing contractor. Your insurer may suggest a preferred vendor, but the decision is generally yours. SimpliRoofs is happy to provide a transparent quote so you can compare and choose with full information.
Same communities.
Brighter tomorrows.
Please note
SimpliRoofs does insurance and storm-damage roof work across Dayton, Cincinnati and the Miami Valley. We inspect and document damage, provide the estimate, meet the adjuster on site and explain the paperwork in plain English. SimpliRoofs is a roofing provider, not an insurance company or public adjuster: we don't adjust, negotiate, or settle claims on your behalf, we don't give insurance or legal advice, and your deductible is always yours. Whether storm damage is covered, and how much your insurer pays, is determined solely by your insurance carrier under the terms of your policy. Our quote documents the cost of the roofing work only; it does not guarantee claim approval, coverage, or any particular settlement amount. Always confirm coverage details directly with your insurer.

Storm damage & insurance
Start with a free inspection and a clear quote.
Get a free, detailed SimpliRoofs quote: the real cost of the work, documented and ready to bring to your insurer. Start online or start with a person.
Prefer to talk? Call or text (937) 966-2141.
Every day, 8am to 7pm.
Get an instant roof price
Type your address, see a real number in about a minute. No visit required, no obligation, nobody chasing you afterward.
Talk with a roofing specialist
A real person walks your roof, explains what they see and helps with the insurance side. Call or text (937) 966-2141.